 All Guides ↗
Your portfolio says a number. Your bank account will say a smaller one. Between the two sit spreads, fees, shipping, and the discount that speed demands, and the gap is wider for exactly the products that look most impressive on a shelf. This guide is about measuring that gap before you need to cross it.
Liquidity is how quickly a position converts to cash, and at what cost. A portfolio mark records what the last buyer paid; it says nothing about what your copies would fetch if you sold this week. Between the sticker and the settlement sit the bid/ask spread, marketplace fees, shipping, and the discount required to sell fast, and every one of those grows as a market gets thinner. A high-velocity modern product might convert at a modest haircut. An aged collectible that trades a few times a month can demand a painful one. Treat every mark as an estimate, and every net-of-friction number as the truth.
In any market, the ask is the lowest price a seller is currently demanding, and the bid is the highest price a buyer is currently offering. The gap between them is the spread, and it is the first, most honest measure of liquidity. In deep markets the spread is a rounding error. In thin ones it can be a double-digit percentage of the price, and the “market price” you see quoted, typically the last completed sale, floats somewhere in that gap, aging by the day.
This is why market value and cash value diverge. The mark on your portfolio answers “what did the last transaction print?” Cash value answers a harsher question: “what will the next transaction print, if I am the seller, and I want it done soon?” For a product that sells dozens of copies a day, those two answers sit close together. For a product that sells twice a month, the last print might be weeks old, set by a patient seller who waited months for the right buyer. Quote that number as your exit price and you are borrowing someone else’s patience.
Here is what actually happens to a mark on its way to becoming money. Every number below is illustrative, the venues, percentages, and costs vary, but the shape of the waterfall is universal.
| Step | Illustrative amount | Running total |
|---|---|---|
| Market price (last-sale mark) | $200.00 | $200.00 |
| Quick-sale discount to move this week (−10%, illustrative) | −$20.00 | $180.00 |
| Marketplace fee (~13% of sale price, illustrative) | −$23.40 | $156.60 |
| Shipping and materials (illustrative) | −$12.00 | $144.60 |
| Realistic net proceeds | — | $144.60 · ~72% of the mark |
Read the order carefully, because it compounds. The quick-sale discount comes off the top, then the fee is charged on the discounted sale price, then fixed costs land on whatever is left. On a $200 product the fixed shipping cost is 6% of the mark; on a $40 product the same envelope-and-label reality is 30%, which is why small positions are structurally worse at converting to cash than the same dollars in fewer, larger items. And the illustrative 10% quick-sale discount is the variable that liquidity actually controls: in a deep market it might be a few percent; in a thin one, finding the impatient exit price can mean undercutting every listed ask.
Two metrics describe a market’s ability to absorb selling. Velocity is how many units actually change hands per day. Depth is how much buying interest exists near the current price, how many buyers stand behind the best bid. High velocity with real depth means your sale is routine. Low velocity means every sale is an event, and depth is discovered the hard way.
Then comes the variable almost everyone ignores: your own size. Selling 1 box and selling 20 boxes of the same product are different markets. One box disappears into the daily flow. Twenty boxes are the daily flow, and possibly the week’s. Push them out at once and you undercut your own remaining listings on the way down; feed them out slowly and you carry weeks of price risk while you wait. A market that absorbs three units a week will take a 20-box position on its own schedule, not yours, and the mark never warned you, because the mark was set by someone selling one.
Every product card on the platform carries daily-sales and weekly-absorption metrics for exactly this reason. Before you size a position, check how many units the market actually clears in a week, and size against that number, not against the price chart. The time to discover a product trades twice a month is before you own twenty of it.
Liquidity tiers are easiest to see side by side. Here are two real products from opposite ends of the spectrum, pulled from the platform’s current data:
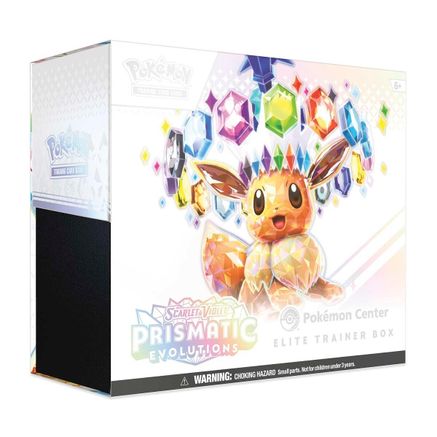

Prismatic Evolutions, a Elite Trainer Box at $411.68, is the high-velocity case: a modern chase product with a broad, active buyer base, where sales print constantly and an exit near the mark is a matter of days. Generations (ETB), a Pokemon at $3,608.50 against a $50.00 MSRP, is the other tier: an aged XY-era collectible whose price reflects years of scarcity, but which trades thinly, with few copies changing hands and patient sellers setting the prints. Both can be excellent holdings. But the same dollar invested in each converts to cash at very different speeds and haircuts, and a portfolio should know which tier every position sits in before the day it needs the answer.
Add it up and the conclusion is uncomfortable but useful: a portfolio marked at last-sale prices systematically overstates its realizable proceeds. Every position carries the waterfall, and the thin ones carry it heaviest. A practical discipline is to keep a second, mental column, a net-of-friction value, that haircuts each mark by its tier: a small trim for the high-velocity products, a serious one for the aged and thinly traded.
None of this makes illiquid product bad. Illiquidity is often the point: the aged collectible trades at its premium precisely because copies rarely surface, and sellers who can wait get paid for waiting. The failure is not owning illiquid positions, it is owning them unknowingly, counting their marks as cash, and discovering the difference during the one week you cannot afford to. Liquidity is not a virtue or a vice. It is a price, and this guide’s only demand is that you know what you are paying.
1. A mark is the last buyer’s opinion, not your exit price. Cash value is what the next transaction pays you, net of everything.
2. Run the waterfall on every position: quick-sale discount, then fees on the discounted price, then fixed costs. Expect roughly a quarter of the sticker to evaporate in translation, more in thin markets.
3. Size against absorption, not against the chart. Selling 20 boxes is a different market from selling 1, and the market decides the schedule.
4. Know each position’s tier. High-velocity products exit near the mark in days; aged, thin ones exit on the market’s timetable or at a real discount.
5. Haircut your portfolio mentally. A net-of-friction view of the same positions is the number that should drive planning, reserves, and sell decisions.
TCG Quant tracks supply, demand, pull rates, destruction, and Long-Term Scores across Pokemon and One Piece sealed product, updated daily.
Explore TCG Quant →