 All Guides ↗
The entire content industry around trading cards points one direction: what to buy. But a return is only real once a position is closed, and nobody talks about closing. This guide is a working framework for the harder half of investing, deciding when the reasons to hold have run out.
Sell when the reason you bought has finished playing out, when the price already assumes the best possible future, when one position has grown too large for the portfolio, when a clearly better use for the capital exists, when the supply picture changes underneath you, or when demand is visibly weakening. And sell, without guilt, when your life needs the money. None of these require predicting a top. Most of the time the right move is not all-or-nothing anyway: scaling out in tranches recovers principal, banks profit, and leaves a free-riding position for the long tail. A sell decision made from a written framework beats one made from a price alert every time.
Every position you will ever own ends in a sale, by you, or eventually by your estate. Yet almost all analysis, community discussion, and content stops at the moment of purchase, as if the trade were complete. It is half a trade. The other half determines the actual return, and it is harder for a structural reason: when you buy, you are fighting only your judgment; when you sell, you are fighting your attachment.
Two biases do most of the damage. Anchoring is the pull of a remembered number, usually your cost or a past peak, that makes today’s price feel wrong regardless of the evidence. The endowment effect is the tendency to value a thing more simply because you own it. Together they produce the classic sealed-investor failure mode: riding a winner up, watching it come all the way back down, and calling the round trip a long-term hold. A framework exists to overrule those instincts with reasons.
For any position, ask: would I buy this product today, at today’s price, in today’s conditions? If the honest answer is no, you are not really holding it. You are re-buying it every day and paying with the money you could have taken off the table.
Six market-facing conditions justify a sale. Each has a visible signature and a proportionate action; none of them is “the price went up, panic.”
| Trigger | What it looks like | Action |
|---|---|---|
| Thesis completion | The re-rating you bought for has happened. The market now prices the scarcity or chase strength you predicted when it was cheap. | Sell or scale out. If you would still buy at today’s price, that is a new thesis; write it down and underwrite it fresh. |
| Best-case valuation | The current price only makes sense if everything goes right: no reprint, demand persists, the chase keeps climbing. | Trim into strength. Let the market pay you for the optimism you no longer have to carry. |
| Concentration | One position has grown past roughly 20–25% of the portfolio, usually by winning. | Trim back toward target weight. You are not selling the product; you are selling the risk. |
| Opportunity cost | A comparable product offers the same thesis at a meaningfully lower multiple. | Rotate. Capital is finite; loyalty to a box is not a strategy. |
| Supply picture changes | A reprint is announced, or fresh product quietly reappears at retail for a set you were holding as scarce. | Reassess immediately. The scarcity clock has been reset, and the thesis is suspended until proven otherwise. |
| Weakening demand | Singles prices sliding, sales velocity falling, listings sitting longer at the same price. | Tighten your timeline and sell into the liquidity that remains, not after it is gone. |
There is a seventh trigger that has nothing to do with markets: personal liquidity needs. Tuition, a house, an emergency. It is always a valid reason to sell, and it is precisely why the portfolio guide insists on a cash reserve and on holding some positions that can be exited quickly. Selling because life requires it is not a failed trade. Being forced to sell the wrong position at the wrong moment is, and that is a planning failure, not a market one.
Thesis completion is the trigger investors resist most, because it arrives disguised as success. Consider a live example:
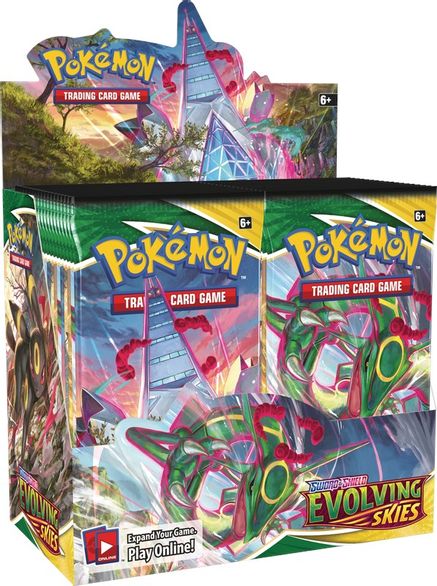
Evolving Skies is the textbook chase-driven set: its alternate-art cards became some of the most wanted in the modern era, boxes were opened relentlessly to find them, and sealed supply thinned exactly the way the destruction thesis predicts. An early buyer’s reasoning, that chase demand would consume supply and re-rate the box, has largely played out. The market price of $2,450.44 against a $143.64 MSRP is the market agreeing with that original thesis, out loud.
Which is the point: holding from here is a different bet than the one the early buyer made. The old bet was “this will be recognized as scarce.” The new bet is “this, already priced as scarce, will become scarcer still.” That second bet might be right! Destruction does not stop. But it is a new thesis at a new price with less margin for error, and it deserves to be underwritten as one, not inherited by default because selling feels like betrayal. This is a framework discussion, not a recommendation to buy or sell this product.
The framework’s most practical tool is the tranche. Instead of one all-or-nothing exit, sell in planned slices at pre-committed levels. Here is the arithmetic, using deliberately round illustrative numbers, not a price prediction for any real product.
Buy 12 boxes at an illustrative $100 each. Total cost basis: $1,200. Everything below follows from that one recorded number.
Proceeds: 4 × $200 = $800. That recovers two-thirds of the original $1,200. Only $400 of principal remains at risk, spread across 8 boxes, an effective $50 per box against a $200 market.
Proceeds: 4 × $300 = $1,200. Cumulative proceeds are now $2,000 against $1,200 invested: all principal recovered plus $800 of banked, realized profit. Nothing that happens next can turn this trade into a loss.
The remaining 4 boxes ride the long tail of the scarcity thesis with none of your original money exposed. This is the position you can hold through any drawdown, because the worst case is a smaller win.
All of that is illustrative arithmetic; real prices will not cooperate so neatly, and tranches may trigger in a different order or not at all. But the structure is the lesson: each slice converts paper gain into certainty, and what remains gets easier to hold, not harder. Scaling out is how you resolve the fight between “the thesis completed” and “destruction continues”, by taking both sides in measured size.
1. Every trade has two halves. A buy without an exit framework is a plan to improvise under emotional pressure.
2. Sell on triggers, not feelings. Thesis completion, best-case pricing, concentration, opportunity cost, supply changes, and weakening demand are conditions you can observe, and a liquidity need in your own life outranks them all.
3. Run the one-question test. If you would not buy it today at today’s price, you are paying to keep it.
4. When a thesis completes, re-underwrite. Holding a winner from a higher price is a new bet, and it should have to earn its place like any other.
5. Scale out in tranches. Recover principal first, bank profit second, and let a risk-free remainder carry the long-term upside.
TCG Quant tracks supply, demand, pull rates, destruction, and Long-Term Scores across Pokemon and One Piece sealed product, updated daily.
Explore TCG Quant →